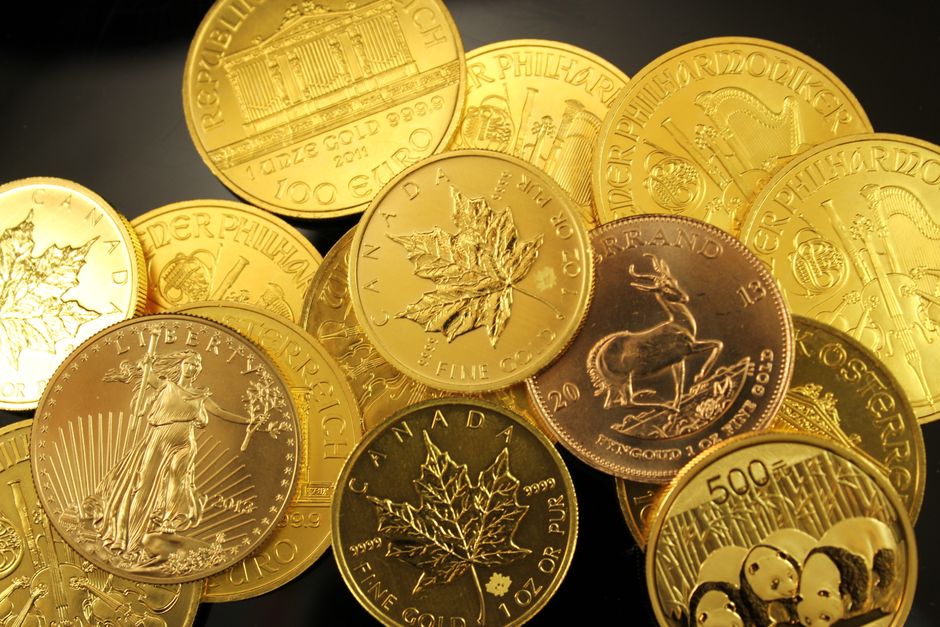
Gold IRA Basics: Rules, Benefits, and Eligibility
By Editorial Team · November 21, 2026
What a Gold IRA Is
A gold individual retirement account, or gold IRA, is a self-directed IRA that can hold certain precious metals alongside or instead of conventional investments. It follows the same broad tax framework as other IRAs, but its investment choices and storage requirements are different. The account is generally administered by a custodian, while an approved depository stores the metals.
Despite the name, a gold IRA does not normally let an owner keep bullion at home. Personal possession can violate IRA rules and may cause the value to be treated as a taxable distribution. Investors typically choose between a traditional account, where eligible contributions may be tax-deductible and withdrawals are generally taxable, and a Roth account, funded with after-tax money and offering tax-free qualified withdrawals.
A gold IRA is not a separate tax category. It is a way to hold approved assets within an existing IRA structure. The account’s tax treatment depends on its type and whether the owner follows the applicable rules.
Eligible Metals and Account Rules
Federal tax rules permit certain gold, silver, platinum, and palladium products in an IRA. Gold generally must meet a minimum fineness of 99.5 percent, with exceptions for specific coins, such as American Gold Eagles. Not every coin or bar qualifies, even if it is made of gold. Collectibles and many numismatic coins are not permitted IRA investments.
The metals must be held by a qualified trustee or custodian, usually at an approved depository. Investors should confirm that the custodian and storage arrangement meet IRS requirements before buying. The account holder cannot use IRA metals personally, pledge them as collateral, or store them at home as if they were ordinary property.
Transactions must also follow IRA rules. Buying metals from a disqualified person, using account assets for personal benefit, or arranging an improper transfer can create tax consequences. Because details matter, investors should ask a tax professional or custodian about a proposed transaction before acting.
Eligibility, Contributions, and Transfers
Most people with taxable compensation can contribute to an IRA, subject to annual contribution limits and other requirements. Traditional IRA deductions can be limited by income and workplace retirement plan coverage. Roth IRA contributions are subject to income limits. These rules apply to gold IRAs as they do to other IRAs, and the annual limit is shared across a person’s traditional and Roth IRA contributions rather than multiplied for each account.
A gold IRA can also receive eligible rollovers or transfers from other retirement accounts. A direct trustee-to-trustee transfer generally moves funds between custodians without the account holder taking possession. Rollovers, where the individual receives a distribution before depositing it into another eligible account, have deadlines and may be subject to withholding or other restrictions. Employer plans can have additional rules, especially while a person is still employed.
Before moving retirement funds, confirm that the receiving account can hold the intended metals and that the transaction qualifies. A mistaken or late rollover can become a taxable distribution, and early withdrawals may also incur an additional tax unless an exception applies.
Potential Benefits and Trade-Offs
Some investors consider gold as a way to diversify a retirement portfolio. Its price can move differently from stocks and bonds at times, and some people view it as a potential store of value during economic uncertainty. Those characteristics may appeal to investors who want exposure to physical commodities within a tax-advantaged account.
Gold does not produce interest or dividends, however, and its price can fall as well as rise. A concentrated allocation may increase portfolio risk rather than reduce it. The metal’s performance can also differ from inflation, so it is not a guaranteed hedge or a reliable source of short-term protection.
Costs deserve close attention. A gold IRA may involve account setup and annual administration fees, storage and insurance charges, and dealer markups or transaction costs. The difference between a dealer’s purchase and buyback prices can also affect returns. These expenses can be higher than those of a standard brokerage IRA, particularly for smaller accounts.
How to Evaluate a Gold IRA
Compare custodians and dealers by reviewing their fee schedules, storage arrangements, product eligibility, transaction procedures, and customer service. Ask whether storage is segregated or commingled, how insurance works, and what it costs to sell or take a distribution in cash or metal. Request written details rather than relying only on verbal claims.
Be cautious of promises of guaranteed profits, claims that gold cannot lose value, or pressure to move retirement savings quickly. A salesperson’s compensation and the price offered for metals can affect the recommendation. Check relevant regulatory and business records, and understand the account’s liquidation process before investing.
A gold IRA may suit some investors, but it is not automatically appropriate for every retirement plan. Consider the role of precious metals in a diversified portfolio, compare costs with other investment options, and consult a qualified tax or financial professional when needed.
Related articles
Business Litigation in Canada: Costs and Options
Understand common business dispute costs in Canada, the main ways to resolve them, and practical steps to manage legal risk before and during a case

Insurance for Older Cars: Coverage and Options in Spain
Compare insurance options for older cars in Spain, from mandatory liability to broader cover, and learn what affects premiums, claims and policy value
Gold IRA Rules, Taxes, and Account Requirements
Learn how gold IRAs work, which metals qualify, how contributions and withdrawals are taxed, and what to know about custodians and storage rules