Gold IRA Rules, Taxes, and Account Requirements
By Editorial Team · November 20, 2026
What a Gold IRA Is
A gold IRA is a self-directed individual retirement account that holds certain precious metals instead of, or alongside, conventional investments. It follows the same broad federal tax framework as other IRAs, but the account must meet additional requirements for eligible metals, custody, and storage. The term “gold IRA” is commonly used, though an account may also hold qualifying silver, platinum, or palladium.
Investors generally choose a traditional or Roth structure. Contributions to a traditional IRA may be tax-deductible depending on income, workplace-plan coverage, and filing status. Investments grow tax-deferred, and withdrawals are generally taxed as ordinary income. Roth IRA contributions are made with after-tax money; qualified withdrawals are generally tax-free. Eligibility and tax treatment depend on the rules in effect and the account holder’s circumstances.
A gold IRA is not a separate tax category. It is a self-directed IRA whose assets are subject to the applicable IRA rules, along with restrictions on collectibles and physical possession.
Eligible Metals and Account Setup
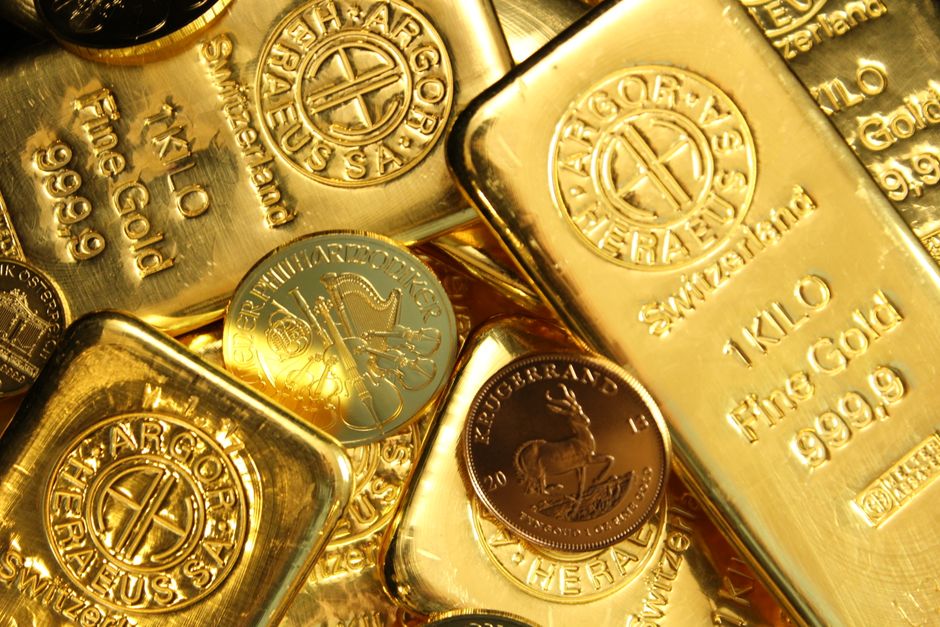
The IRS generally treats precious-metal coins and bullion as collectibles, which IRAs cannot normally hold. An exception allows an IRA to own certain coins and bullion that meet statutory standards. Gold bullion must generally meet a minimum fineness of 99.5 percent. Specific exceptions apply to certain coins, including American Gold Eagles. Silver, platinum, and palladium have their own fineness requirements, and not every product marketed for retirement accounts qualifies.
Before buying, confirm that the exact coin or bar is permitted and that the seller and custodian can document its eligibility. Collectible coins and jewelry typically do not qualify. A dealer’s description or marketing claim does not establish that an item meets IRS requirements.
An IRA must be administered by a qualified trustee or custodian. For a self-directed account, the custodian handles account records, reporting, and transactions, but may not evaluate an investment’s quality or verify every sales claim. Compare fees, services, and procedures before opening an account. Common costs include setup, annual administration, transaction, and storage fees.
Custody and Storage Rules
IRA-owned metals generally must be held by the trustee or an approved custodian, rather than kept personally by the account owner. In practice, metals are stored at a facility arranged through the custodian, often in a segregated or non-segregated arrangement. Ask how ownership is recorded, how metals are insured, and what fees apply to storage and handling.
Taking possession of IRA metals personally, storing them at home, or using them for personal purposes can create a distribution or other tax problem. The rules can be fact-specific, and promotional claims about home storage should be reviewed carefully with a qualified tax professional. The account owner should not assume that forming a limited liability company or using a particular type of safe automatically satisfies IRA custody rules.
A transfer between IRA custodians is often used to fund a gold IRA. A direct trustee-to-trustee transfer generally avoids the account holder receiving the money. A rollover, in which funds are paid to the individual, is subject to timing and other restrictions. Confirm the process with both custodians before moving funds to avoid an unintended taxable distribution.
Contributions, Distributions, and Taxes
Gold IRAs follow the annual contribution limits and eligibility rules for traditional and Roth IRAs. Contribution limits can change, and people age 50 or older may qualify for an additional catch-up contribution. Contributions may be limited by earned income, filing status, or income thresholds, particularly for Roth IRAs. A rollover or transfer is not the same as a regular annual contribution, but it must still follow the applicable rules.
Traditional IRA withdrawals are generally taxable as ordinary income. Taking money out before age 59½ may also trigger a 10 percent additional tax unless an exception applies. Required minimum distributions generally begin at the age set by current law, and the account holder must satisfy them even if the account holds metals. This may require selling assets or taking an eligible in-kind distribution, with the distribution’s value included in taxable income.
Qualified Roth IRA distributions are generally tax-free, but Roth accounts have their own holding-period and age requirements. Distributions of physical metals are valued for tax reporting purposes. The exact tax result can depend on the account type, transaction, and individual circumstances, so consult a tax adviser before arranging a withdrawal.
Evaluating a Gold IRA
A gold IRA can add a different type of asset to a retirement portfolio, but it also brings costs, storage requirements, and rules that do not apply to ordinary brokerage accounts. Metals do not produce interest or dividends, and their prices can rise or fall. Consider how a proposed allocation fits with your time horizon, diversification, and need for liquidity.
Review the custodian agreement, dealer pricing, buyback terms, and all recurring fees. Be cautious of pressure to move retirement savings quickly or claims of guaranteed returns, tax-free access, or risk-free protection. For decisions involving eligibility, transfers, storage, or distributions, consult an independent tax professional or financial adviser familiar with self-directed IRAs.
Related articles
Gold IRA Basics: Rules, Benefits, and Eligibility
Learn how gold IRAs work, which metals qualify, who can contribute, and the costs, tax rules, and risks to consider before investing
Business Litigation in Canada: Costs and Options
Understand common business dispute costs in Canada, the main ways to resolve them, and practical steps to manage legal risk before and during a case

Insurance for Older Cars: Coverage and Options in Spain
Compare insurance options for older cars in Spain, from mandatory liability to broader cover, and learn what affects premiums, claims and policy value