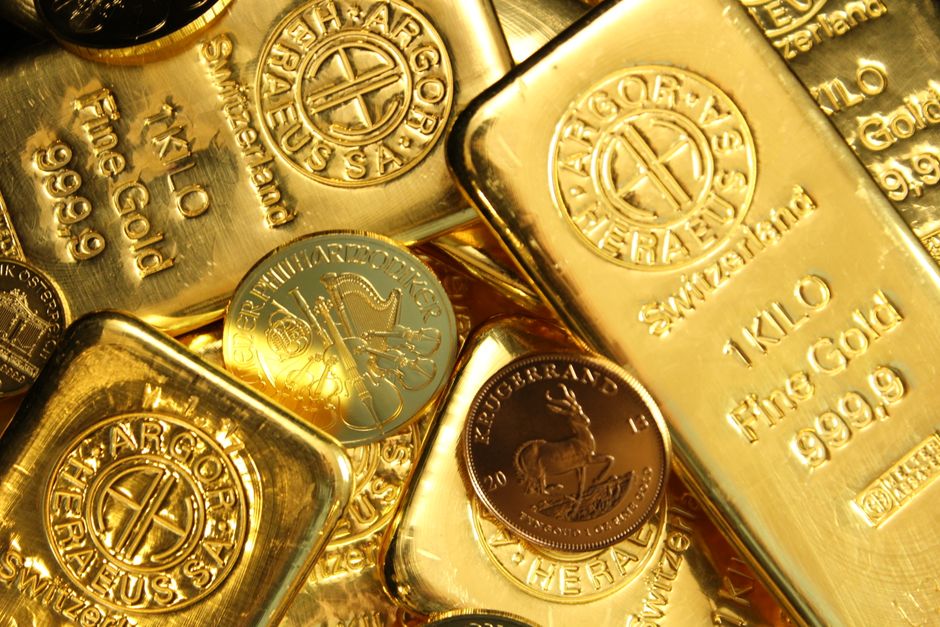
Patriot Gold IRAs and Retirement Account Options in the US
By Editorial Team · November 20, 2026
Understanding a Gold IRA
A gold individual retirement account, often called a Gold IRA, is a self-directed IRA that can hold certain precious metals instead of relying only on conventional investments such as stocks, bonds, and mutual funds. Patriot Gold Group is a precious-metals dealer that offers help with setting up and funding these accounts. As with any provider, investors should review its services, fees, and terms directly before making a decision.
Gold IRAs follow many of the same tax rules as other individual retirement accounts. A traditional account may allow tax-deductible contributions, with withdrawals generally taxed as income. A Roth account is funded with after-tax money, and qualified withdrawals may be tax-free. Eligibility, contribution limits, and distribution rules depend on current IRS requirements and an individual’s circumstances.
The account itself is not the metal. A qualified custodian administers the IRA, while an approved depository stores its assets. IRS rules restrict which precious metals an IRA can hold, including requirements for purity and approved forms. Personal possession of IRA metals is generally not permitted while they remain in the account.
Patriot Gold Group and Provider Services
Precious-metals firms commonly assist customers with account applications, transfers, rollovers, and the selection of eligible products. Patriot Gold Group describes services in these areas, but investors should confirm exactly what is included, who performs each task, and which independent custodian and storage facility will be used.
A dealer’s role differs from a custodian’s. The dealer sells metals, while the custodian handles account administration and reporting. The depository provides storage. Understanding these separate responsibilities can help clarify where fees are charged and whom to contact about account records, transactions, or storage arrangements.
Before opening an account, request a written schedule of costs. Potential charges include account setup, annual administration, storage, insurance, transaction fees, and the difference between a metal’s market price and the dealer’s selling or buyback price. Ask whether fees are flat or based on account value, and whether any introductory offer has conditions. Compare the total expected cost with other providers rather than focusing on a single advertised feature.
Retirement Account Options
A Gold IRA is only one possible way to save for retirement. Workplace plans such as 401(k)s may offer employer matching and access to diversified investment funds. Traditional and Roth IRAs can provide more control over investment choices, though the available assets depend on the account provider. Some self-directed IRAs allow alternative assets, subject to tax rules and custodian policies.
Investors who want exposure to gold do not necessarily need to own physical metal in an IRA. Depending on the account and its investment menu, they may consider publicly traded funds that track gold, shares in mining companies, or other securities related to precious metals. These options have different risks and costs. A fund does not provide direct ownership of specific coins or bars, while mining shares are affected by company performance and operating conditions as well as gold prices.
The right approach depends on goals, time horizon, risk tolerance, and the rest of a household’s finances. Gold can behave differently from stocks and bonds, but its price can fall, it does not produce interest or dividends, and physical holdings involve storage and transaction costs. Concentrating a large share of retirement savings in one asset class can increase risk.
Transfers, Rollovers, and Tax Considerations
People may fund a new account through eligible contributions or by moving money from another retirement account. A direct trustee-to-trustee transfer generally sends assets between custodians. A rollover may involve a distribution to the account holder, followed by a deposit into another eligible account within a required time limit. Mistakes can create taxes or penalties, so investors should verify the process with both institutions and consider professional tax advice.
Not every workplace plan permits an in-service rollover, and not every retirement account can be moved in the same way. Investors should also ask how existing investments will be sold or transferred, when funds will be available, and whether the new account’s fees could offset potential benefits. Avoid making a decision based only on claims about inflation protection or future gold prices; neither is guaranteed.
How to Evaluate a Provider
Compare providers on transparent pricing, product selection, buyback terms, custodian and depository arrangements, customer support, and the paperwork required to open and maintain an account. Ask for all important terms in writing, including how purchases are priced and how a future sale or distribution would work. Check relevant regulatory and consumer-protection resources, and distinguish a company’s marketing statements from independent information.
A precious-metals IRA may suit some investors, but it is not a substitute for a complete retirement plan. Reviewing account options alongside expected income, savings, taxes, and diversification can help put the decision in context. When the tax treatment or transfer rules are unclear, consult a qualified financial or tax professional before moving retirement funds.
Related articles
Gold IRA Basics: Rules, Benefits, and Eligibility
Learn how gold IRAs work, which metals qualify, who can contribute, and the costs, tax rules, and risks to consider before investing
Business Litigation in Canada: Costs and Options
Understand common business dispute costs in Canada, the main ways to resolve them, and practical steps to manage legal risk before and during a case

Insurance for Older Cars: Coverage and Options in Spain
Compare insurance options for older cars in Spain, from mandatory liability to broader cover, and learn what affects premiums, claims and policy value